Wall Street stocks in relief rally after heavy AI-related selloff
By Chibuike Oguh and Marc Jones
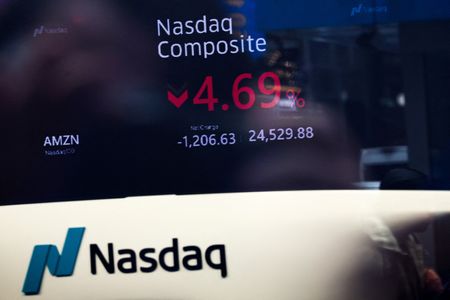
NEW YORK/LONDON, Nov 6 (Reuters) - Wall Street equities mostly rallied on Friday, reversing course after trillions of dollars of world stock market value was wiped out over fears that Democratic election victories this week would bring tighter US regulations for the AI industry.
Benchmark S&P 500 and the Nasdaq were trading higher with technology, communication services and consumer discretionary stocks driving gains. The Dow edged lower on the day. All three indexes were on track for weekly losses following a brutal selloff in the prior session.
The Dow Jones Industrial Average was down 0.08%, the S&P 500 rose 0.71%, and the Nasdaq Composite gained 1.4%.
The Philadelphia Semiconductor Index was up 4.2% after slumping in its biggest one-day drop since April 2025. Nvidia rose 3%, after suffering its worst day since January 2025, when the emergence of low-cost Chinese AI model DeepSeek hammered markets.
Other heavyweight chipmakers, including AMD, Intel, and Micron Technology, were up between 5.5% and 10%, while Elon Musk's Tesla and SpaceX were also up 2% and 8% respectively after losses earlier this week.
"Most of the disruption of the AI buildout will not probably occur but it's just the uncertainty of the change in government from Republican-led to Democratic-led, not only at the federal level but the state, local levels," said Gerry Sparrow, president and portfolio manager at Sparrow Capital Management.
"That's causing some disruption in the expectations of investors... The volatility around elections or any political event, whether it be war or terrorist attack, is always going to disrupt the market."
Texas' Democratic governor-elect Gina Hinojosa said on Thursday that the state — which already has a large share of US data centres — will introduce new laws to protect local communities from their further mass buildup.
The jitters are hitting an AI trade already under pressure from fears that the massive cost of the data centres and other infrastructure will limit future returns, spurring margin calls and spooking retail investors and hedge funds alike.
RIPPLE EFFECT
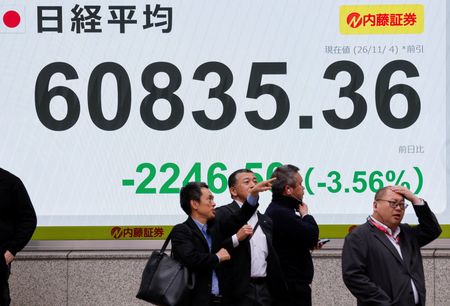
The bounces were in stark contrast with market action in the rest of the world. Europe's STOXX 600 lost 1%. In Asia, Japan's Nikkei and South Korea's KOSPI both slumped about 6%. For the Nikkei — just like Wall Street the previous day — it was the biggest one-day drop since US President Donald Trump's "Liberation Day" trade tariff panic of April 2025.
The MSCI All-World index fell 0.52% while MSCI's broadest index of Asia-Pacific shares outside Japan lost 3%.
PAYROLLS BEAT FORECASTS
US nonfarm payrolls, usually one of the most-focused on pieces of data, but largely overshadowed by the tech drama, showed a stronger-than-expected 165,000 pickup in jobs.
An anticipated slowdown in annual wage growth to below 3% for the first time in nearly 5-1/2 years did not materialise either as it came in at 3.1%.
The yield on the benchmark US 10-year Treasury note ticked up to 4.85%, having dropped to its lowest level since September 9 overnight.
In currencies, the dollar rose against major currencies including the euro, yen and Swiss franc. It was up 0.52% against the yen and rose 0.47% against the Swiss franc. The euro was down 0.68% against the dollar at $1.1142.
Brent crude prices tiptoed back up towards $100 a barrel, but are still set for their biggest weekly drop since 2020 on hopes the midterms' results might prompt Trump to de-escalate the Iran war.
Spot gold fell 0.48% to $4,067.75.
(Reporting by Chibuike Oguh in New York; Editing by Jonathan Spicer and Chizu Nomiyama )
Find it fast
Looking for more insights? Explore our other news sections for updates on sustainable finance, companies and financial education