ECB to keep rates steady as investors focus on French bonds, Lagarde's future
By Francesco Canepa and Balazs Koranyi
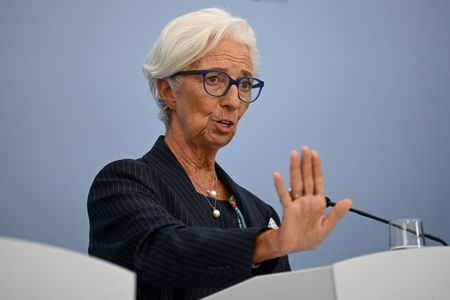
FRANKFURT, Oct 29 (Reuters) - The European Central Bank is set to keep interest rates on hold on Thursday in a well-telegraphed decision that is likely to be overshadowed by questions about bond-market turmoil in France and ECB President Christine Lagarde's own future.
The euro zone's central bank has already raised rates twice since June and is expected to resume tightening in the coming months as policymakers seek to prevent an oil-price shock linked to the Iran war from feeding into other prices and wages.
But it must also contend with a surge in government bond yields — especially in debt-laden France — that has pushed up borrowing costs for households and businesses and which Lagarde has said will curb growth and inflation.
Caught between persistent inflation fuelled by a renewed surge in energy costs and deteriorating financing conditions, the ECB is widely expected to keep its deposit rate at 2.5% while signalling that another increase, potentially as soon as December, remains likely.
"There is likely a low bar to another hike in December, given the likelihood of another upward revision of the ECB's inflation forecast due to higher energy prices," Oliver Rakau at Oxford Economics said.
Such an outlook is consistent with signals from the US Federal Reserve, which left rates unchanged on Wednesday but kept the door open to more tightening, solidifying market bets for an early December move.
Money markets are currently pricing another three rate increases from the ECB by the end of next year, which would take the deposit rate to 3.25%, a level that is widely seen as restricting economic growth.
LAGARDE TO FACE QUESTIONS ABOUT HER FUTURE
Lagarde is set to be quizzed about her own tenure at Thursday's press conference amid speculation she may leave before presidential elections in her native France in the spring, despite having a year left of her ECB term.
An early departure would allow French President Emmanuel Macron and other European Union leaders to fill one of the bloc's most powerful economic positions before a vote that opinion polls suggest could be won by the far right.
Reuters reported this month that the World Economic Forum could appoint Lagarde as its next chair as soon as November, hastening her exit and a wider reshuffle at the top of the ECB.
"It's far from an ideal situation to have any uncertainty around leadership while the central bank grapples with tighter financial conditions, higher energy prices and more uncertainty around the broader macro outlook," Henry Cook, a senior economist at Japanese broker MUFG, said.
The former central bank governors of the Netherlands and Spain, Klaas Knot and Pablo Hernandez de Cos, are seen as frontrunners to replace Lagarde.
FRENCH TURMOIL IN FOCUS BUT NO ACTION
The more immediate challenge for policymakers may be turmoil in bond markets.
A global rise in yields, fuelled by stronger growth expectations, higher debt issuance and massive investment linked to artificial intelligence, is pushing up borrowing costs for governments, households and businesses alike.
In France, investors have become increasingly uneasy about the country's growing debt burden and uncertain fiscal outlook following this year's elections. Concerns have been amplified by suggestions from parts of the political left that debt held by the ECB could be written off.
The result has been a sharp increase in French borrowing costs. France is now paying some of the highest yields in a quarter-century to raise money on bond markets, while the premium investors demand to hold French debt over benchmark German bonds is larger than for any other euro zone country.
That has fuelled speculation that the ECB might be forced to respond, if only verbally for now.
"If you look at the ECB’s sovereign market stress indicator, we're very far away from levels that may trigger intervention," Simon Dangoor at Goldman Sachs said.
"They've typically come up with a new tool that's customised for that specific set of circumstances, and there's a reasonable chance that if we were to go down that path, the ECB would come up with something which is customised to the specific reality of the facts on the ground," Dangoor added.
The ECB's first line of defence would probably be flexible reinvestment of proceeds from bonds acquired during its vast asset-purchase programmes of the previous decade.
Beyond that, it could activate its never-used Transmission Protection Instrument, a scheme designed to counter what policymakers deem unjustified market pressure.
(Editing by Catherine Evans and Sam Holmes)
Find it fast
Looking for more insights? Explore our other news sections for updates on sustainable finance, companies and financial education