Bank of England official says central bank mishandled its first response to Iran shock
By Andy Bruce
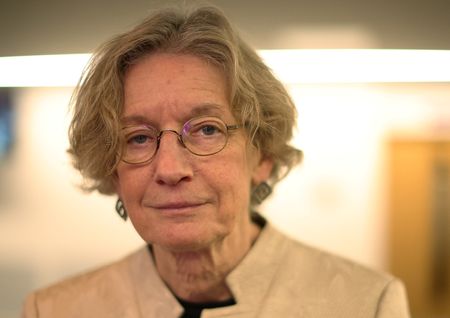
MANCHESTER, England, Oct 1 (Reuters) - Bank of England interest rate-setter Catherine Mann said the central bank made errors in how it framed its policy response to the shock from the Middle East war, and that has pushed up borrowing costs in the UK in ways that should be of no comfort to officials.
Mann said on Thursday that the rise in market interest rates after the outbreak of the Iran war — which some Monetary Policy Committee members think is helping to bear down on inflation — actually reflected expectations of higher inflation and possibly a "monetary policy uncertainty premium".
She traced this risk premium to what she said were errors in the BoE's initial response in March to the outbreak of war in Iran. The BoE held interest rates with a message that she said was perceived by investors as "wait mode", rather than taking necessary action to control inflation.
"Against this backdrop, as a monetary policymaker, I cannot take comfort from tighter nominal financial conditions when much of that tightening reflects a higher inflation risk premium and, possibly, a monetary policy uncertainty premium that our own decisions and communications may have contributed to," Mann said in a speech at the Nomura London Macro Forum.
As a result, higher interest rates being paid by borrowers including households, businesses and the government may just be a reflection of expectations of higher inflation, and not contributing much to slowing future price growth.
This view stands at odds with that of Governor Andrew Bailey and others on the MPC, who have said that the rise in market borrowing costs had bought the BoE time to consider whether it needed to raise rates itself.
CLEAR COMMUNICATION
Mann said uncertainty about the BoE's reaction function — how investors and the public expect it to react to economic developments and inflation threats — should not compound the problem.
An external member of the Monetary Policy Committee, Mann voted to raise rates last month to 4% from 3.75%, against the majority who voted to hold.
Her comments chimed with the view of BoE Chief Economist Huw Pill who has also criticised the central bank's communications as too passive in the face of rising inflation threats.
Mann pointed to BoE research showing that market uncertainty about the interest rate path rose after the March meeting, when it normally falls after decisions, and that such spikes help to lift borrowing costs and tighten financial conditions.
The BoE's decision not to publish a baseline forecast in its quarterly economic projections a month later likely added to the sense of uncertainty around its intentions, Mann said.
"In my view, real financial conditions are insufficiently tight," Mann said.
"The appropriate response therefore is not to rely on risk premia to do the work of policy, but to reduce inflation risk and policy uncertainty through a clearly communicated reaction function and a sufficiently restrictive path for Bank Rate."
(Reporting by Andy Bruce; editing by David Milliken and Toby Chopra)
Find it fast
Looking for more insights? Explore our other news sections for updates on sustainable finance, companies and financial education