Analysis-For Chinese automakers, the road to survival runs through Europe
By Nick Carey
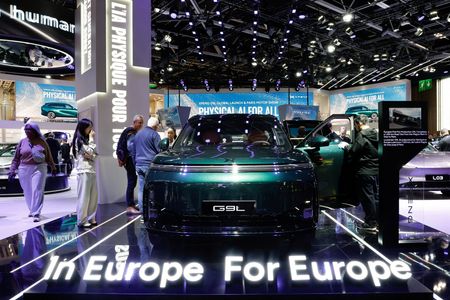
PARIS, Oct 15 (Reuters) - The record 20 Chinese brands vying for attention at this week's Paris car show reflect a stark reality: as a slowdown at home pushes China's overcrowded auto industry to consolidate, success in Europe could help determine which carmakers survive.
With the US market largely closed to Chinese automakers, Europe is by far the most profitable market still open to them, but also one of the toughest to crack.
Chinese brands including BYD, Chery and SAIC's MG have already established a foothold in Europe, while newer entrants are racing to build dealer networks, parts operations and brand recognition.
For some, the stakes are existential.
"If they drop exports in Europe, they die," said Francois Roudier, secretary general of the International Organization of Motor Vehicle Manufacturers (OICA).
The pressure stems from China itself, where the world's largest car market has become increasingly crowded.
More than 100 automakers compete in China, where state support from national, provincial and city governments has helped sustain local champions and delayed long-expected consolidation that could entail significant job losses.
A sales slump, however, has brought that prospect closer.
New car sales in China fell 20% in the first half of this year. Omdia analyst Chris Liu said Chinese automakers, expecting continuing growth, launched an average of three new models a day in 2026.
"This is the worst possible year to launch a new vehicle in China," Liu said.
Recovery is expected to be slow. Consultancy AlixPartners predicts Chinese new-car sales will not return to 2025 levels until after 2030.
The downturn is increasing pressure on automakers to find growth abroad, particularly in Europe.
OICA's Roudier said a new EU-China deal to halve imports of Chinese hybrid cars into the bloc would only intensify competition among automakers at home.
"Now you have to eat your neighbour," he said.
FIRST STEP TOWARDS CONSOLIDATION
Industry executives and analysts say Beijing has begun taking tentative steps towards the consolidation long predicted across the sector.
A merger deal last month involving Toyota's two Chinese joint-venture partners, under which state-owned FAW will become Guangzhou Automobile Group's (GAC) second-largest shareholder, is widely viewed as an early test case.
Analysts say the deal is particularly complex because it involves FAW, which is owned by China's central government, and GAC, which is controlled by Guangdong province. Toyota's involvement adds a foreign private-sector partner to the equation.
"This is probably one of the most complex mergers to manage," said Pedro Pacheco, vice president of research at Gartner.
In a road map published in September outlining plans to become one of the world's leading automotive powers by 2030, China's industry ministry said it would "encourage industry consolidation".
Gartner's Pacheco said Beijing was likely to pursue mergers carefully and methodically.
"They don't want to convey the image externally that there's a sense of urgency or desperation," he said.
Industry experts expect consolidation ultimately to reduce China's crowded auto sector to a handful of globally competitive manufacturers.
"Our assumption is those remaining automakers will have (annual) sales of between 5 million and 6 million cars," said an executive at a major Chinese automaker, who spoke on the condition of anonymity.
EUROPE AS A PROVING GROUND
Analysts say overseas performance, particularly in Europe, is likely to become an increasingly important measure of which automakers can thrive independently.
"China's government will definitely evaluate overseas sales performance, in particular Europe," Omdia's Liu said. "If they do better overseas, the government will say 'you can actually survive on your own.'"
That dynamic favours early movers such as BYD and Chery, which are already rapidly gaining European market share.
Barriers to entry are rising. The best dealer locations are increasingly taken, while new entrants must also invest heavily in parts warehouses, repair networks and after-sales support to meet European customer expectations.
Automakers must also focus on resale values in a market where more than half of new vehicles are leased, a business model that remains rare in China.
Those investments take time and money. Great Wall Motor, for example, struggled in its first attempt to establish itself in Europe and is now working on a comeback.
Changan, which launched European sales last year, began building its dealer network ahead of its market entry and expects to have 650 dealerships across Europe by next year. Executives at the Paris show said the company had deliberately avoided expanding too quickly before introducing a broader model range.
"We don't make fast food," said Vice President Mi Mengdong.
Philip Nothard, insight director at dealer services firm Cox Automotive, said BYD, Chery and MG had been willing to spend heavily to establish themselves in Europe, leaving less room for later arrivals to gain meaningful market share.
"We'll see a big four or five (Chinese automakers), then others who will come and go," he predicted.
(Reporting By Nick Carey. Additional reporting by Qiaoyi Li in Beijing. Editing by Mark Potter)
Find it fast
Looking for more insights? Explore our other news sections for updates on sustainable finance, companies and financial education